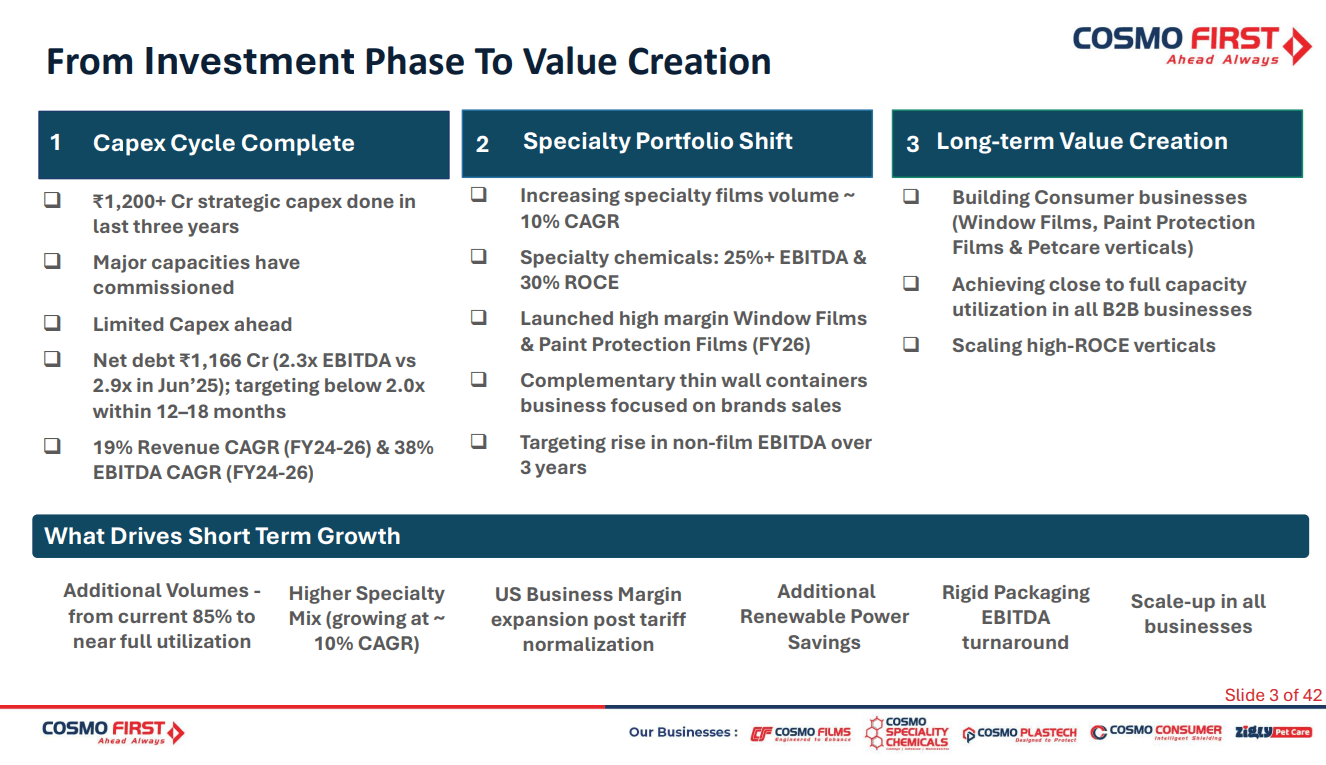
Cosmo First’s Q1 revenue grew 46%, but sales volumes grew only 9%. Most of the gap is higher raw-material prices passed on to customers, which inflates revenue without adding profit.
Measured per kilogram, though, profitability did improve, and the company says its ₹1,200 cr capex cycle is now done. Below are our notes on what’s structural, what’s one-time, and what to check when Q2 results come out., but before that:
Spread the Word: If you think our stock recommendations could add value to your friends, relatives, or acquaintances, we’d appreciate you spreading the word about Katalyst Wealth.
Latest Stock recommendations under Alpha, Alpha +, and Insider Bets memberships you can participate in:
- Insider Bets (Released: 21st Sep ’26) A rare setup: Promoter warrant conversion at a premium to CMP + capacity-led earnings inflection + reasonable valuations. (opens in new tab)Read the full recommendation →
- Alpha & Alpha+ (Released: 31st Aug ’26) A founder-led company quietly transforming from a pure B2B supplier into a fast-scaling consumer-facing retail brand. Revenue and profit have compounded at ~30% and ~35% respectively over the last 3 years, with margins expanding as the business mix shifts (opens in new tab)Read the full recommendation →
Revenue up 46%, volumes up 9%. What actually grew at Cosmo First
Q1 FY27 in numbers (consolidated)
The margin fell, but that’s mainly arithmetic. When raw-material costs rise and are passed through, revenue grows faster than profit, so the margin percentage shrinks even if profit per unit sold is unchanged.
Management’s preferred measure is EBITDA per kg. EBITDA grew 26% on 9% more volume, which works out to about 15% more EBITDA per kg. Other income also fell to about ₹11 cr from ₹25 cr a year ago, so the operating improvement is better than the PAT growth suggests.
Film margins: what’s structural and what isn’t
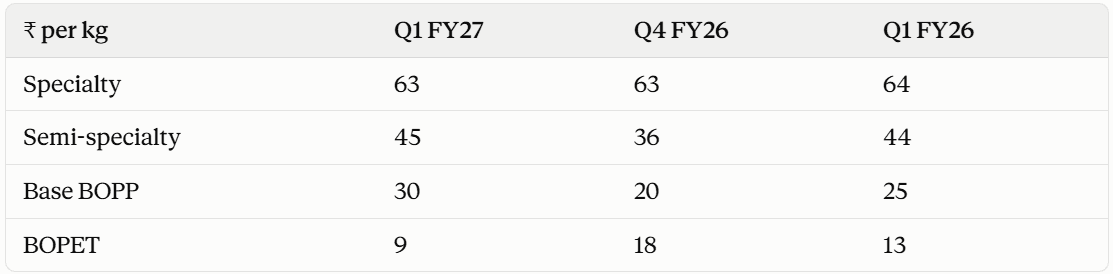
- Base BOPP’s jump to ₹30 includes an inventory gain. When raw-material prices rise, stock bought earlier at lower prices gets sold at the new, higher prices. Management called this non-repetitive but didn’t say how much of the ₹30 it accounts for. Excluding it, they said BOPP margins were “largely flat.”
- Specialty is the stable core. Specialty margins have held above ₹60/kg for five straight quarters. Specialty and semi-specialty films reached 61% of volume, the highest in five quarters, and specialty volume grew 12%. The target is 70%.
- BOPET margins halved quarter-on-quarter. The segment is small (30,000 tonnes of capacity versus 277,000 tonnes of BOPP), and management expects the recently imposed anti-dumping duty to help
Why volumes grew only 9%
- Port congestion: Exports are about half of revenue. Export sales are booked only when the bill of lading is issued, and congestion left an unusually large volume in transit. Export volume fell 13% in the quarter.
- Maintenance: One line was down for a couple of thousand tonnes.
- Tough base: The new BOPP line started mid-Q1 last year, which flatters the year-ago comparison less than it might seem
Management expects some of the in-transit volume to show up in Q2. Film plants ran at 85% utilization, and the 15% headroom is expected to fill over the next two quarters.
Debt: the ratio is improving faster than the debt itself
- Net debt was ₹1,166 cr at end-June, flat versus March even though working capital absorbed ₹85 cr.
- Net debt-to-EBITDA improved to 2.3x from 2.9x a year ago. Most of that came from higher EBITDA. In absolute terms, net debt is slightly higher than June 2025 (₹1,140 cr).
- Targets: below 2x within 12 months (call) or 12–18 months (deck), and a ₹400–500 cr debt reduction over two years as capex stays limited
What management guided
- FY27 revenue: growth of about 20%, with profit growing in line. The four newer businesses are expected to grow about 60%.
- ROCE: from 11% in FY26 to 15–20% within 12–24 months.
- US business: growth of 25–30% after US tariffs on Indian imports were rolled back. The US subsidiary received a refund of about $7 million in July, which hasn’t been booked yet because part of it may be owed to customers.
- Renewable power: ₹25 cr of annual savings, none of it in Q1 yet. One project starts in Q3, the other in Q1 FY28.
- Long term: each of the five businesses could reach ₹500–1,000 cr of revenue in 5–6 years.
We track companies with solid balance sheets, low-key execution, before they show up on everyone’s radar — and break down the numbers that actually matter in our research.
As always, this is not a stock recommendation — This note is for informational purposes only and not a buy/sell recommendation. Please do your own due diligence before investing.
Hope you found the blog post useful and it added value to your investment decisions. Sign up for more interesting stock ideas and industry notes.
Not a research subscriber yet?
If you found this useful, our paid members get full research reports with entry levels, financial models, and entry-exit updates on stocks like these.
(opens in new tab)Explore Katalyst Wealth subscriptions →
Disclaimer: This is not a recommendation to buy/sell any of the stocks mentioned above. The securities quoted are for illustration only and are not recommendatory.
Ekansh Mittal
Research Analyst
SEBI Research Analyst Registration No. INH100001690
Research Analyst Details
Name: Ekansh Mittal Email Id: (opens in new tab)[email protected] Ph: +91 727 5050062
Details of Associate: Not Applicable
Analyst Certification: The Analyst certify (ies) that the views expressed herein accurately reflect his (their) personal view(s) about the subject security (ies) and issuer(s) and that no part of his (their) compensation was, is or will be directly or indirectly related to the specific recommendation(s) or views contained in this research report.
Disclaimer: (opens in new tab)http://www.
Registered Address – 7, Panch Ratan, 7/128, Swaroop Nagar, Kanpur – 208002
Place of Business – 205, Ratan Floor, 113/120, Swaroop Nagar, Kanpur – 208002
Compliance Officer/Grievance Redressal – Mr. Ekansh Mittal, +91-9818866676, (opens in new tab)info@
“Registration granted by SEBI and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors”.
“Investment in securities market are subject to market risks. Read all the related documents carefully before investing.”
The views expressed are based solely on information available publicly and believed to be true. Investors are advised to independently evaluate the market conditions/risks involved before making any investment decision
This report is for the personal information of the authorized recipient and does not construe to be any investment, legal or taxation advice to you. Ekansh Mittal/Mittal Consulting/Katalyst Wealth is not soliciting any action based upon it. This report is not for public distribution and has been furnished to you solely for your information and should not be reproduced or redistributed to any other person in any form. This document is provided for assistance only and is not intended to be and must not alone be taken as the basis for an investment decision. Ekansh Mittal or any of its affiliates or employees shall not be in any way responsible for any loss or damage that may arise to any person from any inadvertent error in the information contained in this report. Neither Ekansh Mittal, nor its employees, agents nor representatives shall be liable for any damages whether direct or indirect, incidental, special or consequential including lost revenue or lost profits that may arise from or in connection with the use of the information. Ekansh Mittal/Mittal Consulting or any of its affiliates or employees do not provide, at any time, any express or implied warranty of any kind, regarding any matter pertaining to this report, including without limitation the implied warranties of merchantability, fitness for a particular purpose, and non-infringement.
The recipients of this report should rely on their own investigations. Ekansh Mittal/Mittal Consulting and/or its affiliates and/or employees may have interests/ positions, financial or otherwise in the securities mentioned in this report. Mittal Consulting has incorporated adequate disclosures in this document. This should, however, not be treated as endorsement of the views expressed in the report.
We submit that no material disciplinary action has been taken on Ekansh Mittal by any regulatory authority impacting Equity Research Analysis.
Use of Artificial Intelligence: RA may infrequently use Artificial Intelligence (AI) tools like chatgpt, notebooklm, etc. in its research services to enhance the quality and efficiency of the recommendations provided to clients. The tools are primarily used for data collection and generating con-call summaries for the purpose of research.
In accordance with Regulation 24(7) of the SEBI (Research Analyst) Regulations, 2014: We take full responsibility for the security, confidentiality, and integrity of client data used in conjunction with AI tools and we ensure compliance with applicable laws regarding the use of AI tools.
Disclaimer: You can access it here – (opens in new tab)LINK
Whether the research analyst or research entity or his associate or his relative has any financial interest in the subject company/companies and the nature of such financial interest – No
Whether the research analyst or research entity or his associates or his relatives have actual/beneficial ownership of 1% or more securities of the subject company (at the end of the month immediately preceding the date of publication of the research report or date of the public appearance) – No
Whether the research analyst or research entity or his associate or his relative has any other material conflict of interest at the time of publication of the research report or at the time of public appearance – No
Whether it or its associates have received any compensation from the subject company in the past twelve months – No
Whether it or its associates have managed or co-managed public offering of securities for the subject company in the past 12 months – No
Whether it or its associates have received any compensation for investment banking or merchant banking or brokerage services from the subject company in the past 12 months – No
Whether it or its associates have received any compensation for products or services other than investment banking or merchant banking or brokerage services from the subject company in the past 12 months – No
Whether the subject company is or was a client during twelve months preceding the date of distribution of the research report and the types of services provided – No
Whether the research analyst has served as an officer, director or employee of the subject company – No
Whether the research analyst or research entity has been engaged in market making activity for the subject company – No