Godawari Power & Ispat (GPIL) owns two iron ore mines that supply ore at about ₹3,400 a tonne. In Q2 it had to buy ore from the market at around ₹6,200, because it ran out of space to dump the waste rock its mines produce.
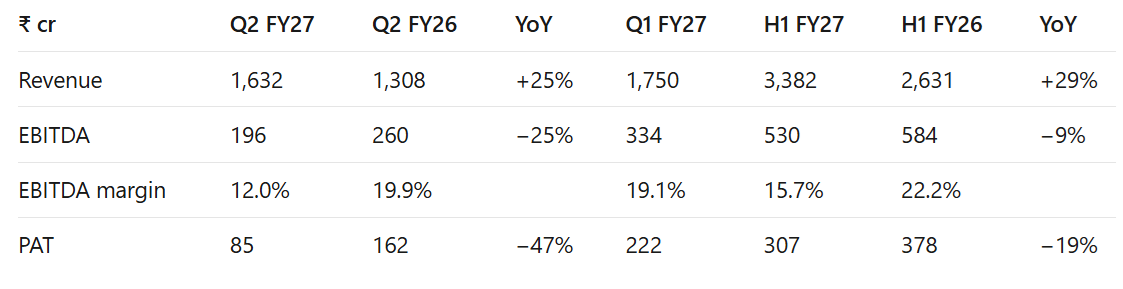
As a result, revenue grew 25% but profit fell 47%. Meanwhile, the company is building a ₹1,400 cr battery factory and targeting 4x revenue by 2030. Our notes from the presentation are below, but before that:
Spread the Word: If you think our stock recommendations could add value to your friends, relatives, or acquaintances, we’d appreciate you spreading the word about Katalyst Wealth.
Latest Stock recommendations under Alpha, Alpha +, and Insider Bets memberships you can participate in:
- Alpha & Alpha+ (Released: 7th Nov ‘26) The world’s largest producer in several niche products, now at the start of an upcycle — fresh capacity in place, a record quarter with EBITDA up 60%, and a long-awaited regulatory approval unlocking high-value markets (opens in new tab)Read the full recommendation →
- Insider Bets (Released: 21st Sep ’26) A rare setup: Promoter warrant conversion at a premium to CMP + capacity-led earnings inflection + reasonable valuations. (opens in new tab)Read the full recommendation →
Revenue flat for four years. The plan: 4x in the next four

Q2 FY27 in numbers (consolidated)
- Costs grew faster than sales. Total expenses rose 37% against 25% revenue growth.
- Interest costs more than doubled, to ₹25 cr from ₹11 cr.
- An unexplained charge: Q2 includes a ₹22 cr exceptional item, which the deck doesn’t explain.
- Quarter-on-quarter, it was worse: EBITDA fell 41% from Q1, because pellet prices also dropped 10%.
The mining bottleneck
Iron ore mining creates large amounts of waste rock (overburden) that has to be dumped nearby. GPIL ran out of permitted space.
- Mining output fell 31% year-on-year, to about 4.5 lakh tonnes.
- Market ore filled the gap: to keep its pellet plants running, GPIL bought ore at market prices. The deck’s own chart puts captive ore at about ₹3,400/t against roughly ₹6,200/t in the market.
- Coal costs also rose, which the company blames on the West Asia crisis.
- One plant was shut: an older 2 MnT pellet plant was temporarily closed as “uneconomical.”
Management’s fix: margins recover “from Q4 FY27”
The deck pins the recovery on two things:
- Overburden dumping permission, which the deck says is “expected shortly.” It doesn’t give a date.
- A 5.4 MnT beneficiation plant (it upgrades lower-grade ore), due in Q3 FY27. ₹258 cr of its ₹325 cr cost has been spent.
Also coming:
- The main mine is expanding. Ari Dongri is permitted to grow from 2.35 MnT to 6 MnT. The ramp-up starts in Q4 FY27, with full output from FY28.
- The new pellet plant is running. It has 4.7 MnT capacity (+74%) and is expected to reach 75% utilization this year.
The big bets: batteries and value-added steel
- Capex still to spend: roughly ₹2,265 cr across projects (my calculation from the deck’s table). For context, FY26 EBITDA was ₹1,253 cr.
- The battery plant is a new business for GPIL. Cells come from China’s EVE Power, and assembly equipment from Lead Intelligent. It has ₹2,795 cr of credit sanctioned, mostly ₹1,995 cr of bank guarantees and letters of credit.
- Why the CRM moved: the project shifted from Chhattisgarh to Maharashtra for state incentives and to sit near the battery plant.
Vision FY 26-2030: an ambitious jump
- Revenue – ₹5,400 cr to ₹24,000 cr
- EBITDA – ₹1,250 cr to ₹3,500 cr
- PAT – ₹802 cr to ₹2,500 cr
- Context: revenue has been flat at about ₹5,400 cr since FY22.
- Margins would fall: the targets imply an EBITDA margin of about 15%, down from 23%. That suggests the battery business will carry much thinner margins than steel.
- The PAT target looks stretched. ₹2,500 cr of PAT on ₹3,500 cr of EBITDA leaves little room for interest, depreciation and tax after this much capex. Incentives may explain the gap, but the deck doesn’t say.
We track companies with solid balance sheets, low-key execution, before they show up on everyone’s radar — and break down the numbers that actually matter in our research.
As always, this is not a stock recommendation — This note is for informational purposes only and not a buy/sell recommendation. Please do your own due diligence before investing.
Hope you found the blog post useful and it added value to your investment decisions. Sign up for more interesting stock ideas and industry notes.
Not a research subscriber yet?
If you found this useful, our paid members get full research reports with entry levels, financial models, and entry-exit updates on stocks like these.
(opens in new tab)Explore Katalyst Wealth subscriptions →
(END)
Disclaimer: This is not a recommendation to buy/sell any of the stocks mentioned above. The securities quoted and for illustration only and are not recommendatory.
Ekansh Mittal
Research Analyst
SEBI Research Analyst Registration No. INH100001690
Research Analyst Details
Name: Ekansh Mittal Email Id: (opens in new tab)[email protected] Ph: (opens in new tab)+91 727 5050062
Details of Associate: Not Applicable
Analyst Certification: The Analyst certify (ies) that the views expressed herein accurately reflect his (their) personal view(s) about the subject security (ies) and issuer(s) and that no part of his (their) compensation was, is or will be directly or indirectly related to the specific recommendation(s) or views contained in this research report.
Disclaimer: (opens in new tab)http://www.
Registered Address – 7, Panch Ratan, 7/128, Swaroop Nagar, Kanpur – 208002
Place of Business – 205, Ratan Floor, 113/120, Swaroop Nagar, Kanpur – 208002
Compliance Officer/Grievance Redressal – Mr. Ekansh Mittal, (opens in new tab)+91-9818866676, (opens in new tab)info@
“Registration granted by SEBI and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors”.
“Investment in securities market are subject to market risks. Read all the related documents carefully before investing.”
The views expressed are based solely on information available publicly and believed to be true. Investors are advised to independently evaluate the market conditions/risks involved before making any investment decision.
This report is for the personal information of the authorized recipient and does not construe to be any investment, legal or taxation advice to you. Ekansh Mittal/Mittal Consulting/Katalyst Wealth is not soliciting any action based upon it. This report is not for public distribution and has been furnished to you solely for your information and should not be reproduced or redistributed to any other person in any form. This document is provided for assistance only and is not intended to be and must not alone be taken as the basis for an investment decision. Ekansh Mittal or any of its affiliates or employees shall not be in any way responsible for any loss or damage that may arise to any person from any inadvertent error in the information contained in this report. Neither Ekansh Mittal, nor its employees, agents nor representatives shall be liable for any damages whether direct or indirect, incidental, special or consequential including lost revenue or lost profits that may arise from or in connection with the use of the information. Ekansh Mittal/Mittal Consulting or any of its affiliates or employees do not provide, at any time, any express or implied warranty of any kind, regarding any matter pertaining to this report, including without limitation the implied warranties of merchantability, fitness for a particular purpose, and non-infringement.
The recipients of this report should rely on their own investigations. Ekansh Mittal/Mittal Consulting and/or its affiliates and/or employees may have interests/ positions, financial or otherwise in the securities mentioned in this report. Mittal Consulting has incorporated adequate disclosures in this document. This should, however, not be treated as endorsement of the views expressed in the report.
We submit that no material disciplinary action has been taken on Ekansh Mittal by any regulatory authority impacting Equity Research Analysis.
Use of Artificial Intelligence: RA may infrequently use Artificial Intelligence (AI) tools like chatgpt, notebooklm, etc. in its research services to enhance the quality and efficiency of the recommendations provided to clients. The tools are primarily used for data collection and generating con-call summaries for the purpose of research.
In accordance with Regulation 24(7) of the SEBI (Research Analyst) Regulations, 2014: We take full responsibility for the security, confidentiality, and integrity of client data used in conjunction with AI tools and we ensure compliance with applicable laws regarding the use of AI tools.
Disclaimer: You can access it here – (opens in new tab)LINK
Whether the research analyst or research entity or his associate or his relative has any financial interest in the subject company/companies and the nature of such financial interest – No
Whether the research analyst or research entity or his associates or his relatives have actual/beneficial ownership of 1% or more securities of the subject company (at the end of the month immediately preceding the date of publication of the research report or date of the public appearance) – No
Whether the research analyst or research entity or his associate or his relative has any other material conflict of interest at the time of publication of the research report or at the time of public appearance – No
Whether it or its associates have received any compensation from the subject company in the past twelve months – No
Whether it or its associates have managed or co-managed public offering of securities for the subject company in the past 12 months – No
Whether it or its associates have received any compensation for investment banking or merchant banking or brokerage services from the subject company in the past 12 months – No
Whether it or its associates have received any compensation for products or services other than investment banking or merchant banking or brokerage services from the subject company in the past 12 months – No
Whether the subject company is or was a client during twelve months preceding the date of distribution of the research report and the types of services provided – No
Whether the research analyst has served as an officer, director or employee of the subject company – No
Whether the research analyst or research entity has been engaged in market making activity for the subject company – No