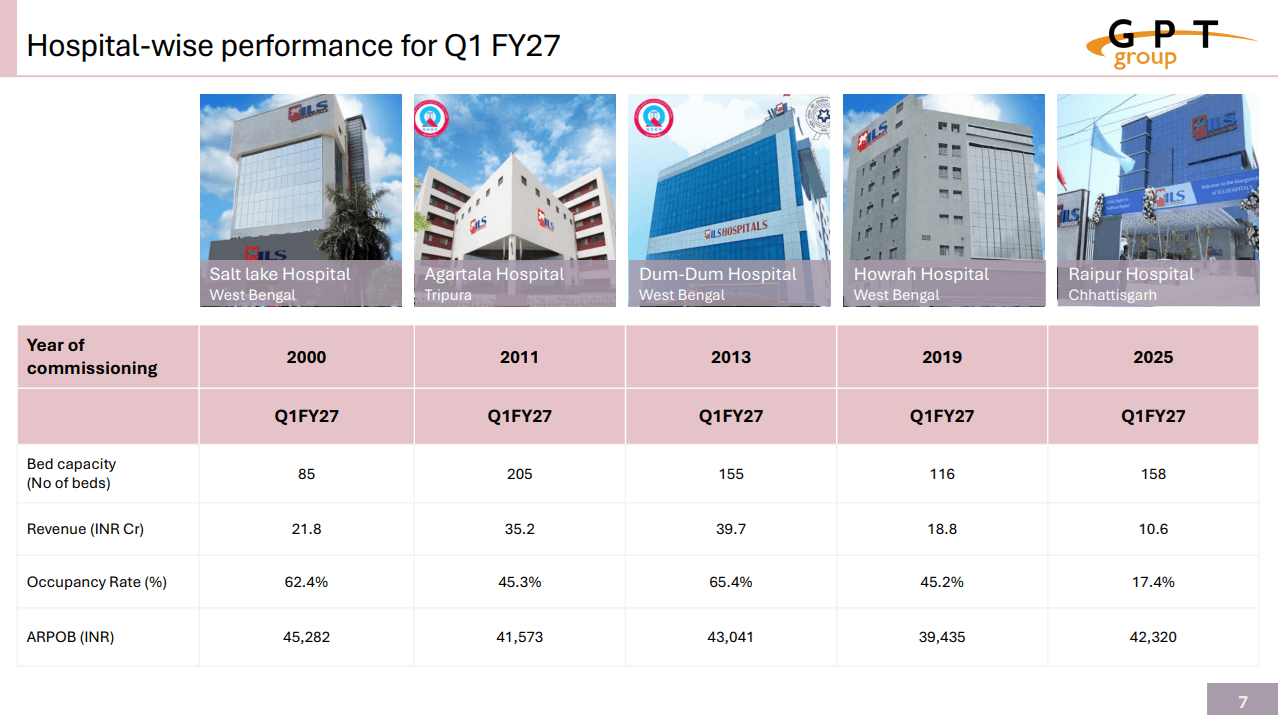
GPT Healthcare’s Q1 numbers looked excellent: revenue grew 18% and profit grew 66%. Network occupancy, however, fell from 53% to 45.5%, and ARPOB rose 9% without any tariff hike.
Both of those facts matter for how you read the next quarter. Below are our notes from the presentation and the concall, organized so you can go into Q2 results knowing what to check, but before that:
Spread the Word: If you think our stock recommendations could add value to your friends, relatives, or acquaintances, we’d appreciate you spreading the word about Katalyst Wealth.
Latest Stock recommendations under Alpha, Alpha +, and Insider Bets memberships you can participate in:
- Insider Bets (Released: 21st Sep ’26) A rare setup: Promoter warrant conversion at a premium to CMP + capacity-led earnings inflection + reasonable valuations. (opens in new tab)Read the full recommendation →
- Alpha & Alpha+ (Released: 31st Aug ’26) A founder-led company quietly transforming from a pure B2B supplier into a fast-scaling consumer-facing retail brand. Revenue and profit have compounded at ~30% and ~35% respectively over the last 3 years, with margins expanding as the business mix shifts (opens in new tab)Read the full recommendation →
GPT Healthcare – This hospital chain’s profit jumped 66%. The real story is one line lower
The quarter in numbers (Q1 FY27 vs Q1 FY26)
- Revenue from operations: ₹126.2 cr, up 17.8%
- EBITDA: ₹26.2 cr, up 38.5%. Margin rose to 20.4% from 17.4%.
- PAT: ₹12.7 cr, up 65.7%
- ARPOB: ₹42,350, up from ₹38,913
- Average length of stay: 3.35 days, down from 3.48
PAT fell 12.6% quarter-on-quarter, but that drop comes from tax. Q4 carried only ₹1.3 cr of tax against ₹4.4 cr this quarter. Profit before tax actually grew 8.2% QoQ.
The occupancy “drop” is mostly Raipur
Raipur is the new 158-bed hospital, and it pulls down the network average. Excluding Raipur, occupancy at the mature hospitals was 58.07%.
Management gave a second reason, which is deliberate. They are cutting length of stay by moving toward shorter, higher-value procedures. That lowers bed-days even when patient count rises. At Agartala, average stay fell from 3.38 to 3 days while inpatient numbers increased.
ARPOB rose without a price increase
Management said no tariff hike was taken this quarter. Their annual, inflation-linked hike happens in October.
They attributed 50–60% of ARPOB growth to specialty and case mix. The revenue split supports this: gastroenterology grew from 5% of revenue in FY26 to 16% in Q1, and interventional cardiology from 9% to 13%. Note that this slide is marked “(Input required)” in the filed deck, so treat the exact figures as provisional.
What management guided
- FY27 EBITDA: about ₹110–115 cr at roughly 21% margin, compared with ₹90.1 cr and 18.8% in FY26. That implies about ₹28–30 cr per quarter for the rest of the year, against ₹26.2 cr in Q1.
- Raipur: occupancy of about 30% by year-end and breakeven around month 20. The hospital opened in May 2025.
- Dum Dum: about 70% occupancy expected to become normal by Q3.
- Bangladesh patient inflows: still below pre-disruption levels. Management expects recovery within about 6 months, helped by visa letters that now name a specific hospital.
- Jamshedpur (155 beds): late Q4 FY27, which could slip to early FY28 if approvals are delayed. About ₹25 cr of debt will be added. Initial ARPOB is expected at ₹38–40k, with breakeven in about 24 months.
- 7th hospital: candidates are Cuttack, Ranchi, Patna, Varanasi and Prayagraj. Both acquisition and greenfield are being considered, with a target of 1,000+ beds within 2 years.
The asset-light model
At Raipur and Jamshedpur, a developer builds the hospital to GPT’s specifications and leases it to GPT long-term. GPT spends its capital on medical equipment rather than real estate.
The trade-off is that rent is recorded as an operating expense, so new hospitals pressure EBITDA margin while they ramp up. Management is using this model to rebuild ROCE, which fell from 28.1% in FY24 to 16.5% in FY26 against a long-term target of 25%.
We track companies with solid balance sheets, low-key execution, before they show up on everyone’s radar — and break down the numbers that actually matter in our research.
As always, this is not a stock recommendation — This note is for informational purposes only and not a buy/sell recommendation. Please do your own due diligence before investing.
Hope you found the blog post useful and it added value to your investment decisions. Sign up for more interesting stock ideas and industry notes.
Not a research subscriber yet?
If you found this useful, our paid members get full research reports with entry levels, financial models, and entry-exit updates on stocks like these.
(opens in new tab)Explore Katalyst Wealth subscriptions →
Disclaimer: This is not a recommendation to buy/sell any of the stocks mentioned above. The securities quoted are for illustration only and are not recommendatory.
Ekansh Mittal
Research Analyst
SEBI Research Analyst Registration No. INH100001690
Research Analyst Details
Name: Ekansh Mittal Email Id: (opens in new tab)[email protected] Ph: +91 727 5050062
Details of Associate: Not Applicable
Analyst Certification: The Analyst certify (ies) that the views expressed herein accurately reflect his (their) personal view(s) about the subject security (ies) and issuer(s) and that no part of his (their) compensation was, is or will be directly or indirectly related to the specific recommendation(s) or views contained in this research report.
Disclaimer: (opens in new tab)http://www.
Registered Address – 7, Panch Ratan, 7/128, Swaroop Nagar, Kanpur – 208002
Place of Business – 205, Ratan Floor, 113/120, Swaroop Nagar, Kanpur – 208002
Compliance Officer/Grievance Redressal – Mr. Ekansh Mittal, +91-9818866676, (opens in new tab)info@
“Registration granted by SEBI and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors”.
“Investment in securities market are subject to market risks. Read all the related documents carefully before investing.”
The views expressed are based solely on information available publicly and believed to be true. Investors are advised to independently evaluate the market conditions/risks involved before making any investment decision
This report is for the personal information of the authorized recipient and does not construe to be any investment, legal or taxation advice to you. Ekansh Mittal/Mittal Consulting/Katalyst Wealth is not soliciting any action based upon it. This report is not for public distribution and has been furnished to you solely for your information and should not be reproduced or redistributed to any other person in any form. This document is provided for assistance only and is not intended to be and must not alone be taken as the basis for an investment decision. Ekansh Mittal or any of its affiliates or employees shall not be in any way responsible for any loss or damage that may arise to any person from any inadvertent error in the information contained in this report. Neither Ekansh Mittal, nor its employees, agents nor representatives shall be liable for any damages whether direct or indirect, incidental, special or consequential including lost revenue or lost profits that may arise from or in connection with the use of the information. Ekansh Mittal/Mittal Consulting or any of its affiliates or employees do not provide, at any time, any express or implied warranty of any kind, regarding any matter pertaining to this report, including without limitation the implied warranties of merchantability, fitness for a particular purpose, and non-infringement.
The recipients of this report should rely on their own investigations. Ekansh Mittal/Mittal Consulting and/or its affiliates and/or employees may have interests/ positions, financial or otherwise in the securities mentioned in this report. Mittal Consulting has incorporated adequate disclosures in this document. This should, however, not be treated as endorsement of the views expressed in the report.
We submit that no material disciplinary action has been taken on Ekansh Mittal by any regulatory authority impacting Equity Research Analysis.
Use of Artificial Intelligence: RA may infrequently use Artificial Intelligence (AI) tools like chatgpt, notebooklm, etc. in its research services to enhance the quality and efficiency of the recommendations provided to clients. The tools are primarily used for data collection and generating con-call summaries for the purpose of research.
In accordance with Regulation 24(7) of the SEBI (Research Analyst) Regulations, 2014: We take full responsibility for the security, confidentiality, and integrity of client data used in conjunction with AI tools and we ensure compliance with applicable laws regarding the use of AI tools.
Disclaimer: You can access it here – (opens in new tab)LINK
Whether the research analyst or research entity or his associate or his relative has any financial interest in the subject company/companies and the nature of such financial interest – No
Whether the research analyst or research entity or his associates or his relatives have actual/beneficial ownership of 1% or more securities of the subject company (at the end of the month immediately preceding the date of publication of the research report or date of the public appearance) – No
Whether the research analyst or research entity or his associate or his relative has any other material conflict of interest at the time of publication of the research report or at the time of public appearance – No
Whether it or its associates have received any compensation from the subject company in the past twelve months – No
Whether it or its associates have managed or co-managed public offering of securities for the subject company in the past 12 months – No
Whether it or its associates have received any compensation for investment banking or merchant banking or brokerage services from the subject company in the past 12 months – No
Whether it or its associates have received any compensation for products or services other than investment banking or merchant banking or brokerage services from the subject company in the past 12 months – No
Whether the subject company is or was a client during twelve months preceding the date of distribution of the research report and the types of services provided – No
Whether the research analyst has served as an officer, director or employee of the subject company – No
Whether the research analyst or research entity has been engaged in market making activity for the subject company – No