Aarti Drugs’ Q1 profit before tax rose 35%, but almost all of the growth came from price. Realizations rose 16–17% year-on-year while volumes grew just 3.5%, helped by raw-material shortages linked to the West Asia conflict.
Management says prices have already started easing. The question for the next few quarters is whether the capacity the company has spent ₹600 cr building can take over from price. Our notes from the presentation and the concall are below, but before that:
Spread the Word: If you think our stock recommendations could add value to your friends, relatives, or acquaintances, we’d appreciate you spreading the word about Katalyst Wealth.
Latest Stock recommendations under Alpha, Alpha +, and Insider Bets memberships you can participate in:
- Insider Bets (Released: 21st Sep ’26) A rare setup: Promoter warrant conversion at a premium to CMP + capacity-led earnings inflection + reasonable valuations. (opens in new tab)Read the full recommendation →
- Alpha & Alpha+ (Released: 31st Aug ’26) A founder-led company quietly transforming from a pure B2B supplier into a fast-scaling consumer-facing retail brand. Revenue and profit have compounded at ~30% and ~35% respectively over the last 3 years, with margins expanding as the business mix shifts (opens in new tab)Read the full recommendation →
₹600 cr capex done, RoCE at 11.5%. Aarti Drugs’ real test starts now
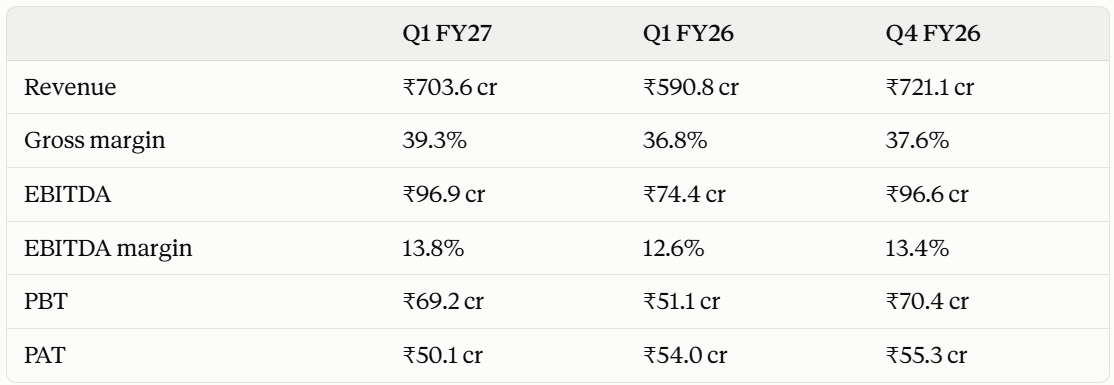
Q1 FY27 in numbers (consolidated)
- The PAT decline is a tax effect. Q1 FY26 included a ₹15 cr tax refund. Excluding it, PAT grew about 29%.
- EBITDA was reduced by a one-time item. It absorbed a ₹2 cr write-off of old capital work-in-progress. Without it, the margin is about 14.1%.
- Quarter-on-quarter, the business was flat. Revenue was down 2% and EBITDA was unchanged, so part of the price benefit had already shown up in Q4.
The growth was mostly price, and price is turning
- Overall, volumes grew 3.5% while realizations rose 16–17%.
- Metformin, the company’s main anti-diabetic API, is priced 15–20% above pre-war levels. Prices peaked in March–April and have eased slightly since.
- Management was direct about this: once the war eases and raw-material costs fall, selling prices will come down too.
- Volumes were held back because drug makers buying the APIs cut purchases when prices spiked. Management expects volume to recover once their inventories run down.
The longer view explains why this price rise matters so much. Over FY24–FY26, Aarti’s prices fell 18%, 13% and 3%, roughly 31% in total, even as volumes grew 7–11% a year. As a result:
- Revenue barely moved, from ₹2,489 cr in FY22 to ₹2,565 cr in FY26.
- RoCE fell from 20.5% to 11.5%.
Where the revenue came from
- Revenue mix: API was 72.5% of revenue, formulations 12.3%, specialty chemicals 11.7% and intermediates 3.5%.
- Specialty chemicals were the standout. Sales were about ₹82 cr, up roughly 149%, almost entirely from the new Sayakha plant.
- Formulations grew only 8%, to ₹81.6 cr, with 74% from exports.
- Domestic outgrew exports (standalone). Domestic sales grew 25% and exports 12%. Exports were 32% of standalone revenue, against about 38% for FY26.
Sayakha: the structural piece
The Sayakha plant makes methylamines, which are key inputs for metformin.
- Utilization is ramping. It reached about 65% in Q1, up from 30% in Q3 FY26 and 40% in Q4.
- Output: about 3,500 tonnes in the quarter. Management said this specialty chemicals run-rate should hold for the next three quarters.
- Captive use is still low. In the June quarter, 60–70% of these intermediates were still bought from outside. Management expects 80–90% to be made in-house by the December quarter.
- Expected benefit: about 1 percentage point of gross margin at peak. Because the plant replaces purchases, most of this shows up in margins rather than revenue.
Salicylic acid: still a drag
- The Tarapur salicylic acid plant produced only 67 tonnes in the whole quarter.
- After Aarti launched this capacity, Chinese producers cut prices sharply. The anti-dumping duty the company was counting on has been delayed by about a year.
- Plan B is a new 350–400 TPM (tonnes per month) plant for salicylic acid derivatives (methyl salicylate and similar products), which are now more profitable. Trial batches have produced 5–10 tonnes.
- The stated goal is breakeven at the plant, not profit.
Regulated markets: the long-term
USFDA API plant (E-22): approved after a 10-year wait. It makes 4–5 products, all currently sold to Europe. US supply hasn’t started, but samples have been sent to customers. A larger USFDA plant is planned on the adjacent plot, with more than double the capacity.
Formulations: an expansion at Baddi should nearly double tablet and capsule capacity. The company has invested ₹200 cr over two years in oncology, which has USFDA and UK approvals.
What management guided
- Volume growth: 10–15% a year over the next two years. Management said 10% is achievable even if salicylic acid doesn’t recover.
- EBITDA margin: “almost there” on 14%, and 15% “should be very easy” once the new plants’ utilization improves.
- The caveat: asked directly, management agreed the current 14% could ease in the short term as prices fall.
We track companies with solid balance sheets, low-key execution, before they show up on everyone’s radar — and break down the numbers that actually matter in our research.
As always, this is not a stock recommendation — This note is for informational purposes only and not a buy/sell recommendation. Please do your own due diligence before investing.
Hope you found the blog post useful and it added value to your investment decisions. Sign up for more interesting stock ideas and industry notes.
Not a research subscriber yet?
If you found this useful, our paid members get full research reports with entry levels, financial models, and entry-exit updates on stocks like these.
(opens in new tab)Explore Katalyst Wealth subscriptions →
Disclaimer: This is not a recommendation to buy/sell any of the stocks mentioned above. The securities quoted are for illustration only and are not recommendatory.
Ekansh Mittal
Research Analyst
SEBI Research Analyst Registration No. INH100001690
Research Analyst Details
Name: Ekansh Mittal Email Id: (opens in new tab)[email protected] Ph: +91 727 5050062
Details of Associate: Not Applicable
Analyst Certification: The Analyst certify (ies) that the views expressed herein accurately reflect his (their) personal view(s) about the subject security (ies) and issuer(s) and that no part of his (their) compensation was, is or will be directly or indirectly related to the specific recommendation(s) or views contained in this research report.
Disclaimer: (opens in new tab)http://www.
Registered Address – 7, Panch Ratan, 7/128, Swaroop Nagar, Kanpur – 208002
Place of Business – 205, Ratan Floor, 113/120, Swaroop Nagar, Kanpur – 208002
Compliance Officer/Grievance Redressal – Mr. Ekansh Mittal, +91-9818866676, (opens in new tab)info@
“Registration granted by SEBI and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors”.
“Investment in securities market are subject to market risks. Read all the related documents carefully before investing.”
The views expressed are based solely on information available publicly and believed to be true. Investors are advised to independently evaluate the market conditions/risks involved before making any investment decision
This report is for the personal information of the authorized recipient and does not construe to be any investment, legal or taxation advice to you. Ekansh Mittal/Mittal Consulting/Katalyst Wealth is not soliciting any action based upon it. This report is not for public distribution and has been furnished to you solely for your information and should not be reproduced or redistributed to any other person in any form. This document is provided for assistance only and is not intended to be and must not alone be taken as the basis for an investment decision. Ekansh Mittal or any of its affiliates or employees shall not be in any way responsible for any loss or damage that may arise to any person from any inadvertent error in the information contained in this report. Neither Ekansh Mittal, nor its employees, agents nor representatives shall be liable for any damages whether direct or indirect, incidental, special or consequential including lost revenue or lost profits that may arise from or in connection with the use of the information. Ekansh Mittal/Mittal Consulting or any of its affiliates or employees do not provide, at any time, any express or implied warranty of any kind, regarding any matter pertaining to this report, including without limitation the implied warranties of merchantability, fitness for a particular purpose, and non-infringement.
The recipients of this report should rely on their own investigations. Ekansh Mittal/Mittal Consulting and/or its affiliates and/or employees may have interests/ positions, financial or otherwise in the securities mentioned in this report. Mittal Consulting has incorporated adequate disclosures in this document. This should, however, not be treated as endorsement of the views expressed in the report.
We submit that no material disciplinary action has been taken on Ekansh Mittal by any regulatory authority impacting Equity Research Analysis.
Use of Artificial Intelligence: RA may infrequently use Artificial Intelligence (AI) tools like chatgpt, notebooklm, etc. in its research services to enhance the quality and efficiency of the recommendations provided to clients. The tools are primarily used for data collection and generating con-call summaries for the purpose of research.
In accordance with Regulation 24(7) of the SEBI (Research Analyst) Regulations, 2014: We take full responsibility for the security, confidentiality, and integrity of client data used in conjunction with AI tools and we ensure compliance with applicable laws regarding the use of AI tools.
Disclaimer: You can access it here – (opens in new tab)LINK
Whether the research analyst or research entity or his associate or his relative has any financial interest in the subject company/companies and the nature of such financial interest – No
Whether the research analyst or research entity or his associates or his relatives have actual/beneficial ownership of 1% or more securities of the subject company (at the end of the month immediately preceding the date of publication of the research report or date of the public appearance) – No
Whether the research analyst or research entity or his associate or his relative has any other material conflict of interest at the time of publication of the research report or at the time of public appearance – No
Whether it or its associates have received any compensation from the subject company in the past twelve months – No
Whether it or its associates have managed or co-managed public offering of securities for the subject company in the past 12 months – No
Whether it or its associates have received any compensation for investment banking or merchant banking or brokerage services from the subject company in the past 12 months – No
Whether it or its associates have received any compensation for products or services other than investment banking or merchant banking or brokerage services from the subject company in the past 12 months – No
Whether the subject company is or was a client during twelve months preceding the date of distribution of the research report and the types of services provided – No
Whether the research analyst has served as an officer, director or employee of the subject company – No
Whether the research analyst or research entity has been engaged in market making activity for the subject company – No