DC Infotech grew revenue 33% to ₹737 cr in FY26 and profit 46%, and management says it is on track for ₹1,000 cr. It now presents itself as an AI-infrastructure and cybersecurity company rather than a hardware distributor.
The balance sheet tells a second story. Receivables rose 61% and inventory 62%, so roughly ₹74 cr went into working capital, more than three times the year’s profit. Our notes from the presentation and the concall are below, but before that:
Spread the Word: If you think our stock recommendations could add value to your friends, relatives, or acquaintances, we’d appreciate you spreading the word about Katalyst Wealth.
Latest Stock recommendations under Alpha, Alpha +, and Insider Bets memberships you can participate in:
- Insider Bets (Released: 21st Sep ’26) A rare setup: Promoter warrant conversion at a premium to CMP + capacity-led earnings inflection + reasonable valuations. (opens in new tab)Read the full recommendation →
- Alpha & Alpha+ (Released: 31st Aug ’26) A founder-led company quietly transforming from a pure B2B supplier into a fast-scaling consumer-facing retail brand. Revenue and profit have compounded at ~30% and ~35% respectively over the last 3 years, with margins expanding as the business mix shifts (opens in new tab)Read the full recommendation →
From box-mover to AI infrastructure: DC Infotech’s ₹1,000 cr plan
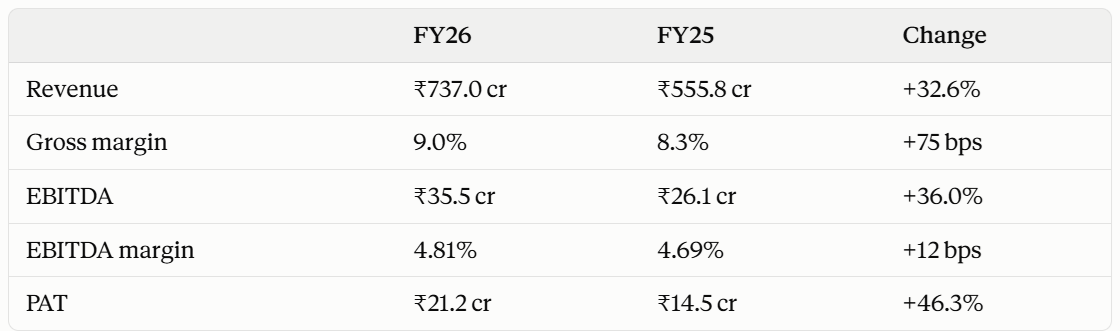
FY26 in numbers (consolidated)
To understand the business model, follow ₹100 of revenue:
- About ₹91 goes to buying the products it resells.
- About ₹4.80 is left as EBITDA.
- Under ₹3 ends up as profit.
That is typical of a distributor. Small improvements in margin matter a lot, and so does how much cash each sale ties up.
Q4: a strong quarter with a forex hit
- Q4 revenue was ₹239.5 cr, up 38.6% year-on-year and 22.2% over Q3.
- EBITDA margin fell to 4.27% from 5.23% in Q3, and PAT fell 12.8% quarter-on-quarter.
- The reason: operating expenses more than doubled, to ₹7.25 cr from ₹3.36 cr in Q3. Management said most of this was an unrealized forex loss on unpaid import bills, caused by the dollar’s rise, and called it one-time.
- The jump of about ₹3.9 cr in expenses is close to 40% of Q4 EBITDA, so Q2 will show whether costs really returned to normal.
The real story: working capital
- Customers pay more slowly. Receivable days rose to about 104 from 86.
- Stock sits longer. Inventory days rose to about 63 from 51.
- The funding came from debt and new equity. Debt-to-equity rose to 0.81 from 0.70. Equity rose ₹35.6 cr against ₹21.1 cr of profit, and share capital went up, which points to roughly ₹14 cr of fresh shares issued. The deck doesn’t explain this.
- Operating cash flow was likely negative. With ₹74 cr going into working capital against ₹21 cr of profit, it very likely was. The deck has no cash-flow statement, so this is my inference.
- Returns fell. RoCE dropped to 18.7% from 21.9%.
Management’s explanation: bigger, multi-technology AI and data-center projects need more capital per order.
Who it sells for
- Brand mix (deck): Samsung 17% of revenue, Arbor 14%, Netgear 10%, D-Link 8%, others 51%.
- Samsung: DC is Samsung’s exclusive partner in India for active LED displays (the screens in boardrooms and auditoriums). It also runs an authorized Samsung service center, which the MD says is the only one in India outside Samsung’s own factory.
- The Samsung number doesn’t match. Asked for Samsung’s share, the MD said ₹150–175 cr (20–24% of revenue). The deck says 17%, or about ₹125 cr.
- NETSCOUT/Arbor (DDoS protection): DC handles 60–70% of their India business.
- Revenue by pillar (call): networking about 30%, unified communication about 36%, cybersecurity about 27%. A few years ago networking was over 50%.
The pivot: services and AI infrastructure
- Services today: software and services are about 20% of revenue (19% in the deck).
- Services target: the MD’s aim is 25% “in a couple of years.” The deck says “double the share of services revenue.” These are quite different goals.
- AI-infrastructure push: the plan is to offer a complete set for AI-ready data centers. DC already sells networking, security and observability tools, and is now adding compute, storage, power, cooling and rack-and-stack.
- Target customers: captive and colocation data centers. Hyperscalers like AWS and Google have their own suppliers.
What management guided
- No numeric guidance for FY27. The ₹1,000 cr revenue aspiration was raised by an analyst, and the MD said the company is “on track.”
- Margins: no target given. The MD said only “better than this.”
- Top three priorities: complete the AI-infrastructure product set, win larger solution-led projects, and build offerings for emerging AI-related security threats.
We track companies with solid balance sheets, low-key execution, before they show up on everyone’s radar — and break down the numbers that actually matter in our research.
As always, this is not a stock recommendation — This note is for informational purposes only and not a buy/sell recommendation. Please do your own due diligence before investing.
Hope you found the blog post useful and it added value to your investment decisions. Sign up for more interesting stock ideas and industry notes.
Not a research subscriber yet?
If you found this useful, our paid members get full research reports with entry levels, financial models, and entry-exit updates on stocks like these.
(opens in new tab)Explore Katalyst Wealth subscriptions →
Disclaimer: This is not a recommendation to buy/sell any of the stocks mentioned above. The securities quoted are for illustration only and are not recommendatory.
Ekansh Mittal
Research Analyst
SEBI Research Analyst Registration No. INH100001690
Research Analyst Details
Name: Ekansh Mittal Email Id: (opens in new tab)[email protected] Ph: +91 727 5050062
Details of Associate: Not Applicable
Analyst Certification: The Analyst certify (ies) that the views expressed herein accurately reflect his (their) personal view(s) about the subject security (ies) and issuer(s) and that no part of his (their) compensation was, is or will be directly or indirectly related to the specific recommendation(s) or views contained in this research report.
Disclaimer: (opens in new tab)http://www.
Registered Address – 7, Panch Ratan, 7/128, Swaroop Nagar, Kanpur – 208002
Place of Business – 205, Ratan Floor, 113/120, Swaroop Nagar, Kanpur – 208002
Compliance Officer/Grievance Redressal – Mr. Ekansh Mittal, +91-9818866676, (opens in new tab)info@
“Registration granted by SEBI and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors”.
“Investment in securities market are subject to market risks. Read all the related documents carefully before investing.”
The views expressed are based solely on information available publicly and believed to be true. Investors are advised to independently evaluate the market conditions/risks involved before making any investment decision
This report is for the personal information of the authorized recipient and does not construe to be any investment, legal or taxation advice to you. Ekansh Mittal/Mittal Consulting/Katalyst Wealth is not soliciting any action based upon it. This report is not for public distribution and has been furnished to you solely for your information and should not be reproduced or redistributed to any other person in any form. This document is provided for assistance only and is not intended to be and must not alone be taken as the basis for an investment decision. Ekansh Mittal or any of its affiliates or employees shall not be in any way responsible for any loss or damage that may arise to any person from any inadvertent error in the information contained in this report. Neither Ekansh Mittal, nor its employees, agents nor representatives shall be liable for any damages whether direct or indirect, incidental, special or consequential including lost revenue or lost profits that may arise from or in connection with the use of the information. Ekansh Mittal/Mittal Consulting or any of its affiliates or employees do not provide, at any time, any express or implied warranty of any kind, regarding any matter pertaining to this report, including without limitation the implied warranties of merchantability, fitness for a particular purpose, and non-infringement.
The recipients of this report should rely on their own investigations. Ekansh Mittal/Mittal Consulting and/or its affiliates and/or employees may have interests/ positions, financial or otherwise in the securities mentioned in this report. Mittal Consulting has incorporated adequate disclosures in this document. This should, however, not be treated as endorsement of the views expressed in the report.
We submit that no material disciplinary action has been taken on Ekansh Mittal by any regulatory authority impacting Equity Research Analysis.
Use of Artificial Intelligence: RA may infrequently use Artificial Intelligence (AI) tools like chatgpt, notebooklm, etc. in its research services to enhance the quality and efficiency of the recommendations provided to clients. The tools are primarily used for data collection and generating con-call summaries for the purpose of research.
In accordance with Regulation 24(7) of the SEBI (Research Analyst) Regulations, 2014: We take full responsibility for the security, confidentiality, and integrity of client data used in conjunction with AI tools and we ensure compliance with applicable laws regarding the use of AI tools.
Disclaimer: You can access it here – (opens in new tab)LINK
Whether the research analyst or research entity or his associate or his relative has any financial interest in the subject company/companies and the nature of such financial interest – No
Whether the research analyst or research entity or his associates or his relatives have actual/beneficial ownership of 1% or more securities of the subject company (at the end of the month immediately preceding the date of publication of the research report or date of the public appearance) – No
Whether the research analyst or research entity or his associate or his relative has any other material conflict of interest at the time of publication of the research report or at the time of public appearance – No
Whether it or its associates have received any compensation from the subject company in the past twelve months – No
Whether it or its associates have managed or co-managed public offering of securities for the subject company in the past 12 months – No
Whether it or its associates have received any compensation for investment banking or merchant banking or brokerage services from the subject company in the past 12 months – No
Whether it or its associates have received any compensation for products or services other than investment banking or merchant banking or brokerage services from the subject company in the past 12 months – No
Whether the subject company is or was a client during twelve months preceding the date of distribution of the research report and the types of services provided – No
Whether the research analyst has served as an officer, director or employee of the subject company – No
Whether the research analyst or research entity has been engaged in market making activity for the subject company – No