Alivus Life Sciences (formerly Glenmark Life Sciences) saw sales to its largest customer, former parent Glenmark Pharmaceuticals, fall 53% in Q1. Total revenue still grew 6%, and profit grew 32%.
The rest of the business grew 26.5%, mostly on volume, and margins hit a record. But to meet its own full-year guidance, Alivus now needs the best three quarters in its history. Our notes from the presentation and the concall are below, but before that:
Spread the Word: If you think our stock recommendations could add value to your friends, relatives, or acquaintances, we’d appreciate you spreading the word about Katalyst Wealth.
Latest Stock recommendations under Alpha, Alpha +, and Insider Bets memberships you can participate in:
- Insider Bets (Released: 21st Sep ’26) A rare setup: Promoter warrant conversion at a premium to CMP + capacity-led earnings inflection + reasonable valuations. (opens in new tab)Read the full recommendation →
- Alpha & Alpha+ (Released: 31st Aug ’26) A founder-led company quietly transforming from a pure B2B supplier into a fast-scaling consumer-facing retail brand. Revenue and profit have compounded at ~30% and ~35% respectively over the last 3 years, with margins expanding as the business mix shifts (opens in new tab)Read the full recommendation →
₹880 cr cash, zero debt, ₹540 cr capex: Alivus Life’s next phase
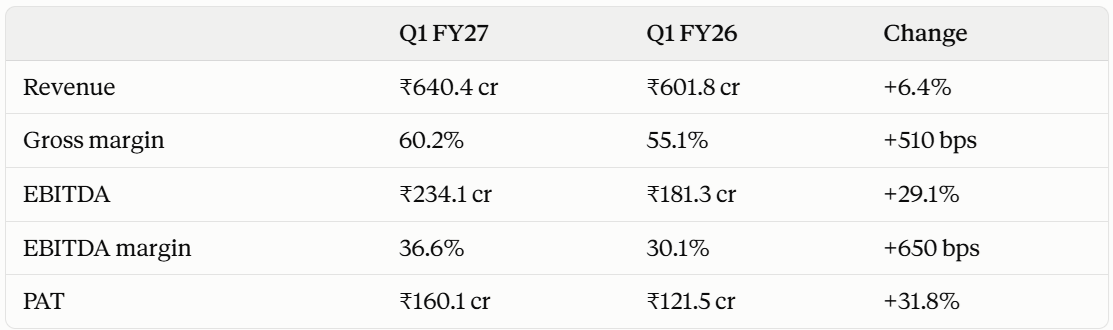
Q1 FY27 in numbers
Other income flatters the margin.
- Alivus counts other income in EBITDA, and other income jumped to ₹22.4 cr from ₹9.0 cr. Management also said forex gains helped margins.
- Excluding other income, the operating EBITDA margin was about 33.1%, against about 28.6% a year ago.
- That is still a strong improvement, just smaller than the headline 650 bps.
Two businesses moving in opposite directions
- Sales to Glenmark down 53% YOY in Q1 and share of revenue down to 11% from 25%
- Management called the decline “inventory rationalization”: Glenmark is using up stock it already holds.
- Q4 FY26 was unusually strong at ₹243.9 cr, so Glenmark had stocked up.
- Alivus supplies Glenmark with more than 50 commercial products. The CEO said that in the worst case, Glenmark sales will be flat for FY27.
Non-GPL growth is genuine volume growth.
- Of the 26.5% growth, about 7 percentage points came from a weaker rupee.
- In constant currency, growth was about 20%: volumes rose 21–22% while prices fell 1–2%.
- New product launches drove it, with growth across all regions.
- Management confirmed that non-GPL business earns higher margins than Glenmark business.
- So the record margin is partly because Glenmark’s share collapsed.
- That also means margins should come down when Glenmark orders return
The guidance math
- Guidance: FY27 revenue growth of 10–12%, weighted toward the second half, with EBITDA margins of 30–32%.
- What it requires: that implies ₹2,807–2,858 cr of revenue. With ₹640 cr done, the next three quarters must average ₹722–739 cr each. The best quarter so far was ₹689 cr (Q4 FY26).
- “Flat” Glenmark is a big ask: Glenmark bought about ₹742 cr in FY26. To stay flat after Q1’s ₹72 cr, it needs about ₹670 cr over Q2–Q4, roughly 14% more than in the same three quarters last year.
- Why the margin guidance is below Q1: the CEO said margins “even up to 34%” are possible, but the war’s effect on raw-material costs (solvents first, now key starting materials) makes him cautious. The CFO added that a Glenmark recovery would pull steady-state margins to about 34%.
Balance sheet and pipeline
- Cash and debt: free cash flow was ₹90 cr in Q1. Cash and investments total ₹880 cr, with no debt.
- Capex: about ₹540 cr planned for FY27 (₹85 cr spent in Q1).
- Acquisitions: the company is looking for synergistic acquisitions: new technology platforms or pipelines, not extra capacity.
- R&D: spending was 3.7% of sales, heading to about 4%. The company has filed 617 drug master files (DMFs) and their European equivalents (CEPs).
- Highly potent APIs (29 products, about $82 bn market): 13 are validated. Revenue starts with patent expiries at the end of calendar 2027, so it is mostly an FY28 story.
- Iron compounds: one regulatory filing has been made, targeting a market of about $2.6 bn.
We track companies with solid balance sheets, low-key execution, before they show up on everyone’s radar — and break down the numbers that actually matter in our research.
As always, this is not a stock recommendation — This note is for informational purposes only and not a buy/sell recommendation. Please do your own due diligence before investing.
Hope you found the blog post useful and it added value to your investment decisions. Sign up for more interesting stock ideas and industry notes.
Not a research subscriber yet?
If you found this useful, our paid members get full research reports with entry levels, financial models, and entry-exit updates on stocks like these.
(opens in new tab)Explore Katalyst Wealth subscriptions →
Disclaimer: This is not a recommendation to buy/sell any of the stocks mentioned above. The securities quoted are for illustration only and are not recommendatory.
Ekansh Mittal
Research Analyst
SEBI Research Analyst Registration No. INH100001690
Research Analyst Details
Name: Ekansh Mittal Email Id: (opens in new tab)[email protected] Ph: +91 727 5050062
Details of Associate: Not Applicable
Analyst Certification: The Analyst certify (ies) that the views expressed herein accurately reflect his (their) personal view(s) about the subject security (ies) and issuer(s) and that no part of his (their) compensation was, is or will be directly or indirectly related to the specific recommendation(s) or views contained in this research report.
Disclaimer: (opens in new tab)http://www.
Registered Address – 7, Panch Ratan, 7/128, Swaroop Nagar, Kanpur – 208002
Place of Business – 205, Ratan Floor, 113/120, Swaroop Nagar, Kanpur – 208002
Compliance Officer/Grievance Redressal – Mr. Ekansh Mittal, +91-9818866676, (opens in new tab)info@
“Registration granted by SEBI and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors”.
“Investment in securities market are subject to market risks. Read all the related documents carefully before investing.”
The views expressed are based solely on information available publicly and believed to be true. Investors are advised to independently evaluate the market conditions/risks involved before making any investment decision
This report is for the personal information of the authorized recipient and does not construe to be any investment, legal or taxation advice to you. Ekansh Mittal/Mittal Consulting/Katalyst Wealth is not soliciting any action based upon it. This report is not for public distribution and has been furnished to you solely for your information and should not be reproduced or redistributed to any other person in any form. This document is provided for assistance only and is not intended to be and must not alone be taken as the basis for an investment decision. Ekansh Mittal or any of its affiliates or employees shall not be in any way responsible for any loss or damage that may arise to any person from any inadvertent error in the information contained in this report. Neither Ekansh Mittal, nor its employees, agents nor representatives shall be liable for any damages whether direct or indirect, incidental, special or consequential including lost revenue or lost profits that may arise from or in connection with the use of the information. Ekansh Mittal/Mittal Consulting or any of its affiliates or employees do not provide, at any time, any express or implied warranty of any kind, regarding any matter pertaining to this report, including without limitation the implied warranties of merchantability, fitness for a particular purpose, and non-infringement.
The recipients of this report should rely on their own investigations. Ekansh Mittal/Mittal Consulting and/or its affiliates and/or employees may have interests/ positions, financial or otherwise in the securities mentioned in this report. Mittal Consulting has incorporated adequate disclosures in this document. This should, however, not be treated as endorsement of the views expressed in the report.
We submit that no material disciplinary action has been taken on Ekansh Mittal by any regulatory authority impacting Equity Research Analysis.
Use of Artificial Intelligence: RA may infrequently use Artificial Intelligence (AI) tools like chatgpt, notebooklm, etc. in its research services to enhance the quality and efficiency of the recommendations provided to clients. The tools are primarily used for data collection and generating con-call summaries for the purpose of research.
In accordance with Regulation 24(7) of the SEBI (Research Analyst) Regulations, 2014: We take full responsibility for the security, confidentiality, and integrity of client data used in conjunction with AI tools and we ensure compliance with applicable laws regarding the use of AI tools.
Disclaimer: You can access it here – (opens in new tab)LINK
Whether the research analyst or research entity or his associate or his relative has any financial interest in the subject company/companies and the nature of such financial interest – No
Whether the research analyst or research entity or his associates or his relatives have actual/beneficial ownership of 1% or more securities of the subject company (at the end of the month immediately preceding the date of publication of the research report or date of the public appearance) – No
Whether the research analyst or research entity or his associate or his relative has any other material conflict of interest at the time of publication of the research report or at the time of public appearance – No
Whether it or its associates have received any compensation from the subject company in the past twelve months – No
Whether it or its associates have managed or co-managed public offering of securities for the subject company in the past 12 months – No
Whether it or its associates have received any compensation for investment banking or merchant banking or brokerage services from the subject company in the past 12 months – No
Whether it or its associates have received any compensation for products or services other than investment banking or merchant banking or brokerage services from the subject company in the past 12 months – No
Whether the subject company is or was a client during twelve months preceding the date of distribution of the research report and the types of services provided – No
Whether the research analyst has served as an officer, director or employee of the subject company – No
Whether the research analyst or research entity has been engaged in market making activity for the subject company – No