Parag Milk Foods, the maker of Gowardhan ghee, Go Cheese and Avvatar whey, posted its highest-ever quarter: revenue of ₹1,241 cr, up 23%. Milk costs rose 18%, yet it earned more per litre than a year ago.
Our notes from the presentation and the concall are below, but before that:
Spread the Word: If you think our stock recommendations could add value to your friends, relatives, or acquaintances, we’d appreciate you spreading the word about Katalyst Wealth.
Latest Stock recommendations under Alpha, Alpha +, and Insider Bets memberships you can participate in:
- Alpha & Alpha+ (Released: 7th Nov ‘26) The world’s largest producer in several niche products, now at the start of an upcycle — fresh capacity in place, a record quarter with EBITDA up 60%, and a long-awaited regulatory approval unlocking high-value markets (opens in new tab)Read the full recommendation →
- Insider Bets (Released: 21st Sep ’26) A rare setup: Promoter warrant conversion at a premium to CMP + capacity-led earnings inflection + reasonable valuations. (opens in new tab)Read the full recommendation →
India’s only whey protein maker grew this business 71%
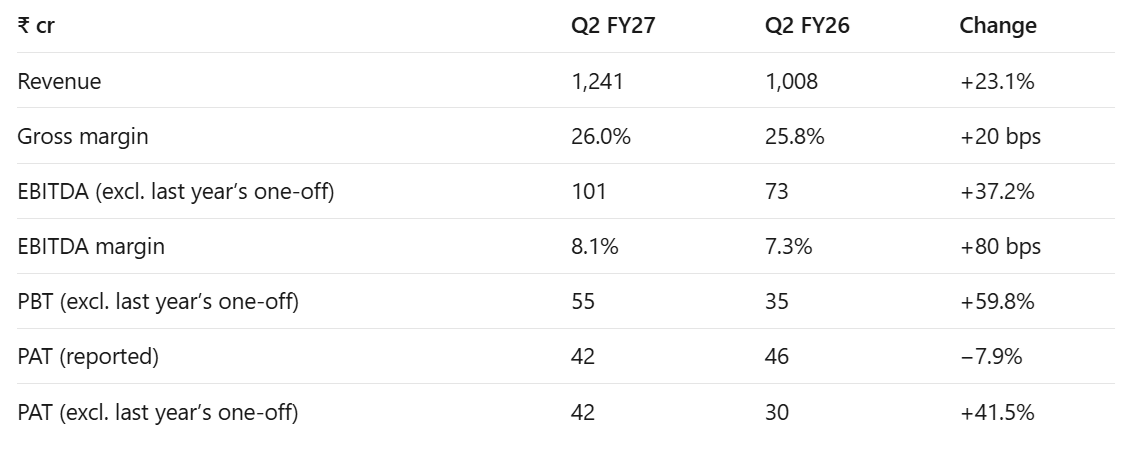
Q2 FY27 in numbers (consolidated)
- Last year had a one-off. Q2 FY26 included a ~₹16 cr gain: a forex mark-to-market charge was reversed once foreign-currency bonds converted into shares. Remove it, and profit grew 42%.
- The company now pays tax. Current tax started this year, which is why PAT grew slower than PBT.
- Half-year view: H1 revenue grew 17.5% to ₹2,185 cr. PAT excluding the one-off grew 11.9% to ₹64 cr, but the PAT margin slipped to 2.9% from 3.1%.
Per-litre economics: passing on the cost
- Milk got much more expensive. It cost ₹7 more per litre, but revenue per litre rose ₹10. Two price hikes during the quarter and a richer product mix did the work.
- Volume: procurement was 21 lakh litres a day, up 5%.
- Cost pressure isn’t easing. Milk is now ₹46.5 a litre. Management expects no usual winter softening this year because of poor rains and drought, though it also doesn’t plan further price hikes soon.
Growth break up
- Flagship growth was mostly price. Volumes grew only 7% against 20% value growth. Volumes were down about 2% in Q1, so this is a recovery.
- Ingredients did more than they usually do. This B2B segment drove nearly 30% of the growth, but it grew just 1% a year from FY22 to FY26. Management credits a shift from skimmed milk powder to higher-value milk protein and lactose. Whether that holds is a key question.
- New Age keeps scaling. It is now 12% of revenue, up from 4% two years ago, and runs at more than ₹600 cr a year. Avvatar is India’s only whey protein brand made from domestic whey, and claims about 15% of online whey sales
Margins: better than they look?
- One-time ad spend: the CSO said about ₹20 cr of Q2 spending was extra, non-recurring brand investment (TV, the KBC sponsorship, influencers). Annual ad spend has stayed within ₹130–150 cr for three years.
- Adjusted margin: adding that back gives a Q2 EBITDA margin of about 9.7%, against the reported 8.1% (my calculation). Management didn’t confirm a “double-digit” margin when asked.
- Gross margin guidance: stable at 26–27%. New Age products should lift it over time, but inflation offsets that for now.
Capacity: paneer ×4, cheese ×2
- The paneer bet: management says about 70–80% of paneer eaten outside homes is unbranded or “analogue” (made with vegetable fats). States are now tightening rules on this, and the COO expects about 80% utilization right after the new capacity starts.
- Competition: Milky Mist is also expanding paneer capacity sharply. Management sees no price war, citing its brands and distribution.
- Whey goes with cheese: doubling cheese doubles whey output too, which feeds Avvatar.
- Restructuring: the board also approved merging Bhagyalaxmi Dairy Farms (the Pride of Cows farm subsidiary) into the parent
Regions and guidance
- Regions: West is 58% of sales (+26%), North 20% (+18%), South 14% (+31%), East 8% (+17%).
- Guidance: no number for FY27. Management targets high single-digit volume growth in core categories, and its long-term aspiration is ₹10,000 cr of revenue with New Age at about 25%.
We track companies with solid balance sheets, low-key execution, before they show up on everyone’s radar — and break down the numbers that actually matter in our research.
As always, this is not a stock recommendation — This note is for informational purposes only and not a buy/sell recommendation. Please do your own due diligence before investing.
Hope you found the blog post useful and it added value to your investment decisions. Sign up for more interesting stock ideas and industry notes.
Not a research subscriber yet?
If you found this useful, our paid members get full research reports with entry levels, financial models, and entry-exit updates on stocks like these.
(opens in new tab)Explore Katalyst Wealth subscriptions →
Disclaimer: This is not a recommendation to buy/sell any of the stocks mentioned above. The securities quoted are for illustration only and are not recommendatory.
Ekansh Mittal
Research Analyst
SEBI Research Analyst Registration No. INH100001690
Research Analyst Details
Name: Ekansh Mittal Email Id: (opens in new tab)[email protected] Ph: +91 727 5050062
Details of Associate: Not Applicable
Analyst Certification: The Analyst certify (ies) that the views expressed herein accurately reflect his (their) personal view(s) about the subject security (ies) and issuer(s) and that no part of his (their) compensation was, is or will be directly or indirectly related to the specific recommendation(s) or views contained in this research report.
Disclaimer: (opens in new tab)http://www.
Registered Address – 7, Panch Ratan, 7/128, Swaroop Nagar, Kanpur – 208002
Place of Business – 205, Ratan Floor, 113/120, Swaroop Nagar, Kanpur – 208002
Compliance Officer/Grievance Redressal – Mr. Ekansh Mittal, +91-9818866676, (opens in new tab)info@
“Registration granted by SEBI and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors”.
“Investment in securities market are subject to market risks. Read all the related documents carefully before investing.”
The views expressed are based solely on information available publicly and believed to be true. Investors are advised to independently evaluate the market conditions/risks involved before making any investment decision
This report is for the personal information of the authorized recipient and does not construe to be any investment, legal or taxation advice to you. Ekansh Mittal/Mittal Consulting/Katalyst Wealth is not soliciting any action based upon it. This report is not for public distribution and has been furnished to you solely for your information and should not be reproduced or redistributed to any other person in any form. This document is provided for assistance only and is not intended to be and must not alone be taken as the basis for an investment decision. Ekansh Mittal or any of its affiliates or employees shall not be in any way responsible for any loss or damage that may arise to any person from any inadvertent error in the information contained in this report. Neither Ekansh Mittal, nor its employees, agents nor representatives shall be liable for any damages whether direct or indirect, incidental, special or consequential including lost revenue or lost profits that may arise from or in connection with the use of the information. Ekansh Mittal/Mittal Consulting or any of its affiliates or employees do not provide, at any time, any express or implied warranty of any kind, regarding any matter pertaining to this report, including without limitation the implied warranties of merchantability, fitness for a particular purpose, and non-infringement.
The recipients of this report should rely on their own investigations. Ekansh Mittal/Mittal Consulting and/or its affiliates and/or employees may have interests/ positions, financial or otherwise in the securities mentioned in this report. Mittal Consulting has incorporated adequate disclosures in this document. This should, however, not be treated as endorsement of the views expressed in the report.
We submit that no material disciplinary action has been taken on Ekansh Mittal by any regulatory authority impacting Equity Research Analysis.
Use of Artificial Intelligence: RA may infrequently use Artificial Intelligence (AI) tools like chatgpt, notebooklm, etc. in its research services to enhance the quality and efficiency of the recommendations provided to clients. The tools are primarily used for data collection and generating con-call summaries for the purpose of research.
In accordance with Regulation 24(7) of the SEBI (Research Analyst) Regulations, 2014: We take full responsibility for the security, confidentiality, and integrity of client data used in conjunction with AI tools and we ensure compliance with applicable laws regarding the use of AI tools.
Disclaimer: You can access it here – (opens in new tab)LINK
Whether the research analyst or research entity or his associate or his relative has any financial interest in the subject company/companies and the nature of such financial interest – No
Whether the research analyst or research entity or his associates or his relatives have actual/beneficial ownership of 1% or more securities of the subject company (at the end of the month immediately preceding the date of publication of the research report or date of the public appearance) – No
Whether the research analyst or research entity or his associate or his relative has any other material conflict of interest at the time of publication of the research report or at the time of public appearance – No
Whether it or its associates have received any compensation from the subject company in the past twelve months – No
Whether it or its associates have managed or co-managed public offering of securities for the subject company in the past 12 months – No
Whether it or its associates have received any compensation for investment banking or merchant banking or brokerage services from the subject company in the past 12 months – No
Whether it or its associates have received any compensation for products or services other than investment banking or merchant banking or brokerage services from the subject company in the past 12 months – No
Whether the subject company is or was a client during twelve months preceding the date of distribution of the research report and the types of services provided – No
Whether the research analyst has served as an officer, director or employee of the subject company – No
Whether the research analyst or research entity has been engaged in market making activity for the subject company – No