Blog

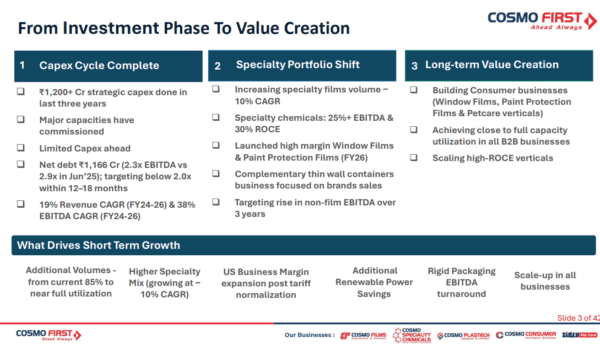
Cosmo First presentation

[Stock idea]: Cosmo First – ₹1,200 cr of capex is done. Now Cosmo First has to prove the returns

Cosmo First’s Q1 revenue grew 46%, but sales volumes grew only 9%. Most of the gap is higher raw-material prices passed on to customers, which inflates revenue without adding profit. Measured per kilogram, though, profitability did improve, and the company says its ₹1,200 cr capex cycle is now done. Below are our notes on what’s structural, what’s one-time, and what to check when Q2 results come out., but before that: Spread the Word: If you think our stock recommendations could…
Read More
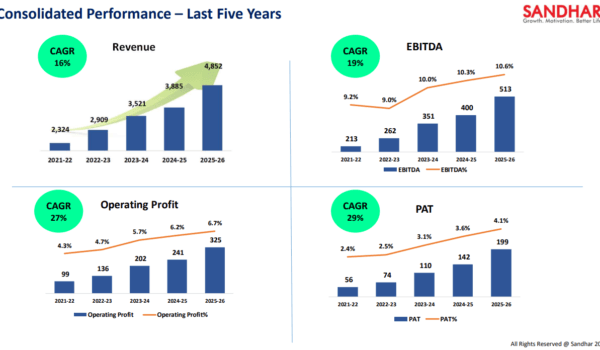
Sandhar financial performance

[Stock idea]: Sandhar Technologies – Company wants to double revenue every 3–4 years

Sandhar Technologies closed FY26 with record revenue of ₹4,852 cr, up 25%, and PAT up 40%. Its reported EBITDA margin also improved, from 10.3% to 10.6%. That margin, however, includes other income, and other income jumped from ₹17 cr to ₹75 cr in FY26, mostly from one-time asset sales. Our notes below separate the growth that’s real from the growth that’s one-time, but before that: Spread the Word: If you think our stock recommendations could add value to your friends, relatives,…

Read More
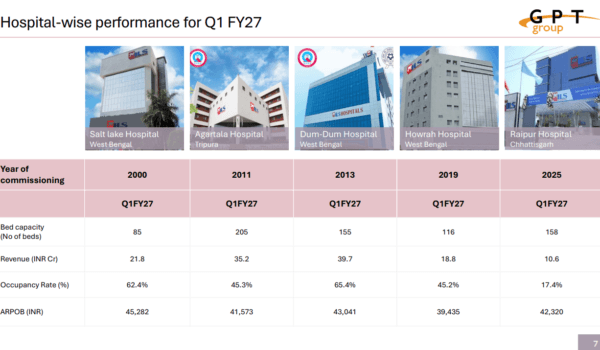
GPT hospital wise performance

[Stock idea]: GPT Healthcare – PAT up 66%, but occupancy fell. Here’s why that’s okay (for now)

GPT Healthcare’s Q1 numbers looked excellent: revenue grew 18% and profit grew 66%. Network occupancy, however, fell from 53% to 45.5%, and ARPOB rose 9% without any tariff hike. Both of those facts matter for how you read the next quarter. Below are our notes from the presentation and the concall, organized so you can go into Q2 results knowing what to check, but before that: Spread the Word: If you think our stock recommendations could add value to your friends,…

Read More

[Sep’26] New Insider Bets stock recommendation dropping tonight

We’re releasing a new stock recommendation tonight under Insider Bets subscription. The Setup: Why this stock caught our attention – Promoter warrant conversion at a premium to CMP + capacity-led earnings inflection + reasonable valuations: Insider conviction, not just words: In FY24, the promoter group was allotted around 1 crore convertible warrants. They’ve since converted every single one – committing over ₹100 crore of personal capital – even as the stock now trades below that price. Promoters don’t usually pay…

Read More